
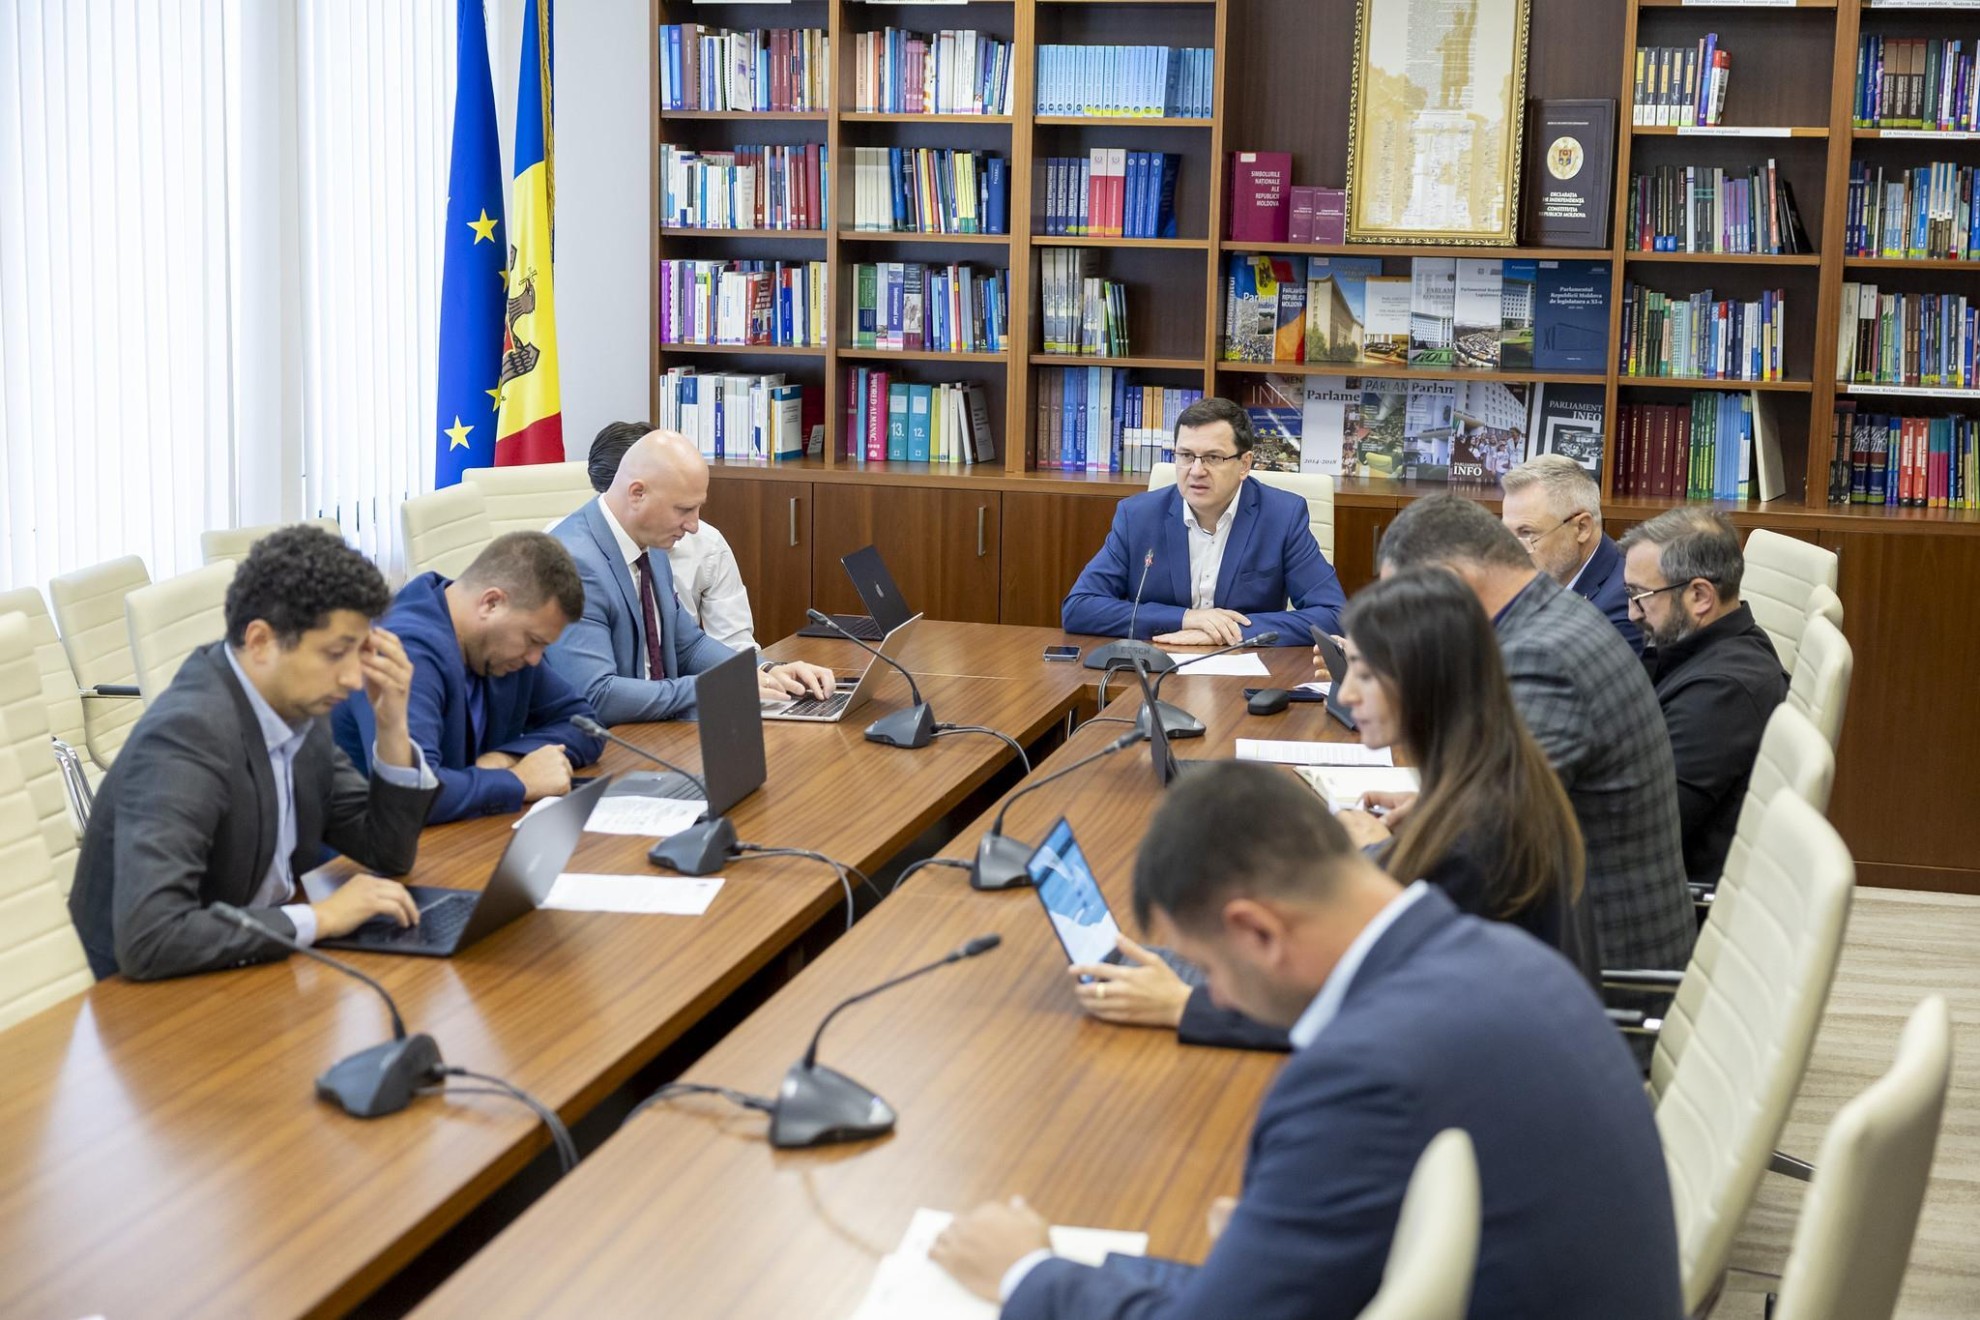
National legislation on direct taxation to be aligned with European Union rules
Chișinău, September 30, 2026 – National legislation on direct taxation will be aligned with European Union rules. The Committee on Economy, Budget and Finance approved the report on a draft law concerning the taxation of interest, royalties and dividends, as well as the introduction of rules on controlled foreign companies and the resolution of tax disputes.

The legislative initiative was drafted by the Ministry of Finance in the context of accelerating the process of harmonizing national legislation with the European Union legal framework. The amendments are necessary because, within the EU single market, transactions carried out between entities from different member states should not be subject to a more or less favorable tax regime. Thus, once the Republic of Moldova joins the EU, the current provisions of national legislation will no longer be applicable.

The Tax Code will be supplemented with a new chapter providing for the elimination of any form of taxation of interest and royalties in the Member State from which these payments originate. Accordingly, income sourced in the Republic of Moldova will be exempt from withholding income tax only if the beneficial owner is a company from an EU Member State or a permanent establishment of a company from a Member State. The exemption from taxation will apply only under certain conditions expressly established by law.

The draft law also transposes into national legislation the Directive on the common tax regime applicable to parent companies and subsidiaries from different member states, which aims to eliminate double taxation of income distributed between subsidiaries and parent companies in the European Union. It is important to note that these companies must be tax residents in the EU and must be subject to corporate income tax, without the possibility of opting for another tax regime or benefiting from an exemption. A parent company is a commercial company from an EU member state that holds at least 10% of the capital of a commercial company in another member state.

Another amendment to the Tax Code concerns the introduction of rules applicable to controlled foreign companies (CFCs). These rules aim to tax profits transferred by groups of companies to controlled subsidiaries in low-tax jurisdictions. The CFC rules provide for the attribution of certain income of a controlled foreign company subject to low taxation to the parent company, with a view to taxing that income in the parent company's country of tax residence. Consequently, the parent company will be required to tax this income in its country of tax residence.

The draft law also contains provisions on mechanisms for resolving tax disputes.

The draft law on direct taxes will be examined in its first reading by the plenary of Parliament.

Following adoption, the new legislative provisions will enter into force on the date the Republic of Moldova accedes to the European Union. In addition, the provisions concerning controlled foreign companies will enter into force on January 1, 2028, while those concerning tax dispute resolution mechanisms will enter into force on January 1, 2027.


Communication and Public Relations Department of the Parliament of the Republic of Moldova
 Facebook
 Instagram
 X/Twitter
 Telegram
Nearly 500 children took up President’s reading challenge
Prime Minister meets with UN Secretary-General
Prime Minister at UN: Moldova may never become great power, but it can certainly become great country
Speech by Prime Minister at 81st Session of United Nations General Assembly
Prime Minister discusses European integration and strengthening economic cooperation with Croatian and Slovenian counterparts in New York
“A Night Written in Red” - documentary performance about courage, resistance and freedom staged in Parliament square
Strengthening Moldova’s cooperation with UNDP, UNOPS discussed in New York
Moldova's National Crisis Management Commission approves new measures to ensure energy security, protect water resources
Moldovan PM, U.S. investors, companies discuss potential projects in Moldova
Head of state says Moldovans must build economy where well-educated people can find opportunities at home
Moldova represented at Interparliamentary Conference on Stability, Economic Coordination and Governance in European Union
Public buildings of Moldova to undergo energy renovation with World Bank's support
President’s speech at ASEM’s 35th anniversary
Moldovan PM meets Dutch counterpart
Vision for administrative reform at district level to be presented Thursday in Chișinău
Government to seek long-term contracts for gas purchases and prepare higher winter compensation
Moldova strengthens cooperation with Danube states to develop inland waterway transport
New state secretary appointed to Health Ministry
 National Bank of Moldova

More financing and development opportunities for small and medium-sized enterprises
Moldova’s energy strategy for 2026–2050 approved by Government
Prime Minister holds talks with World Bank Group representatives
More efficient, transparent controls for business environment in Moldova
Deputy PM for reintegration has meeting with first resident Ambassador of Estonia to Moldova

European Commissioner to visit Chișinău for talks on Growth Plan and economic integration into EU
Speaker after new drone incident: Russia must and will answer for war crimes
Prime Minister holds talks with World Bank Group representatives
VIDEO // Explosion in Hîrbovăț. Drone that flew over airspace of Moldova crashed outside village
Moldovan energy minister, officials from Ireland, Norway, Canada, Lithuania discuss opportunities of cooperation in energy field
More efficient, transparent controls for business environment in Moldova
Deputy PM for reintegration has meeting with first resident Ambassador of Estonia to Moldova
Moldovan economic development minister says ministry to ease administrative burden on entrepreneurs
PHOTO // Moldova included in strategic transport cooperation plan
Norway to provide support for strengthening defense capabilities of Moldova
PHOTO // Moldovan PM, ambassadors of EU member states discuss priorities, reforms for advancing European path
USM students to benefit from internships at Krakow University of Economics
Speaker on opposition’s initiative to suspend head of state: Maia Sandu was elected President by nearly 1 million citizens, who called for and expect us to become EU member state
Prime Minister urges Moldovan companies to prepare for and harness economic opportunities generated by Ukraine’s reconstruction
Presidency, following opposition initiative to suspend head of state: Maia Sandu won trust of more than 930,000 citizens to preserve peace and European path
Prime Minister and Norway’s Ambassador approach strengthening Moldovan-Norwegian relations, continuing joint projects
Receive the latest news directly to your email

Receive the latest news directly to your email